date_range
Thursday 24 Sep 2026


 LOCAL EDITION
close
 LOCAL EDITION


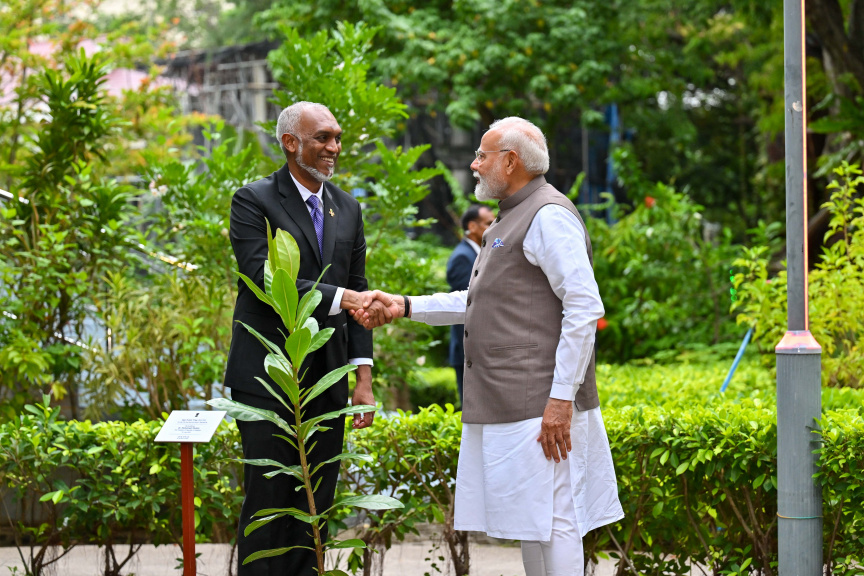
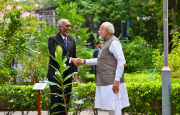
Maldivian President Dr. Mohamed Muizzu (L) and Indian Prime Minister Narendra Modi (R) shake hands during a visit to Male' on July 25, 2025. (Photo/President's Office)
The Reserve Bank of India (RBI) has confirmed that the INR 48.50 billion (USD 506.58 million) line of credit extended to the Maldives with the support of the Indian government officially came into effect on August 27.
According to Reuters, an RBI circular stated that financing under the facility will be released through individual agreements for specific projects. The central bank also specified that each project covered by such an agreement must have a minimum value of INR 5 billion.
Under the terms of the facility, at least 75 percent of the goods and services required for eligible projects must be sourced from Indian companies, while the remaining 25 percent may be procured from other countries. The RBI also clarified that funds provided under the credit line cannot be used to cover commissions payable to export agencies, with exporters required to meet such costs separately.
The credit facility was initially agreed upon in July last year to support the financing of various development projects in the Maldives through the Export-Import Bank of India (Exim Bank).
The activation of the facility comes as the Maldivian government completed the repayment of the final installment of a USD 150 million Treasury bill (T-bill) issued to the State Bank of India (SBI) last week. According to the Ministry of Finance, the debt, which was incurred during the administration of former President Ibrahim Mohamed Solih, was repaid in three installments. The first USD 50 million was paid in January 2024, followed by a further USD 50 million in May, while the remaining USD 50 million was settled on September 17th through the Sovereign Development Fund (SDF). The Indian Ministry of External Affairs confirmed that the USD 45 million in interest accrued on the T-bill over a five-year period was covered by the Indian government.