date_range
Friday 09 Oct 2026


 LOCAL EDITION
close
 LOCAL EDITION


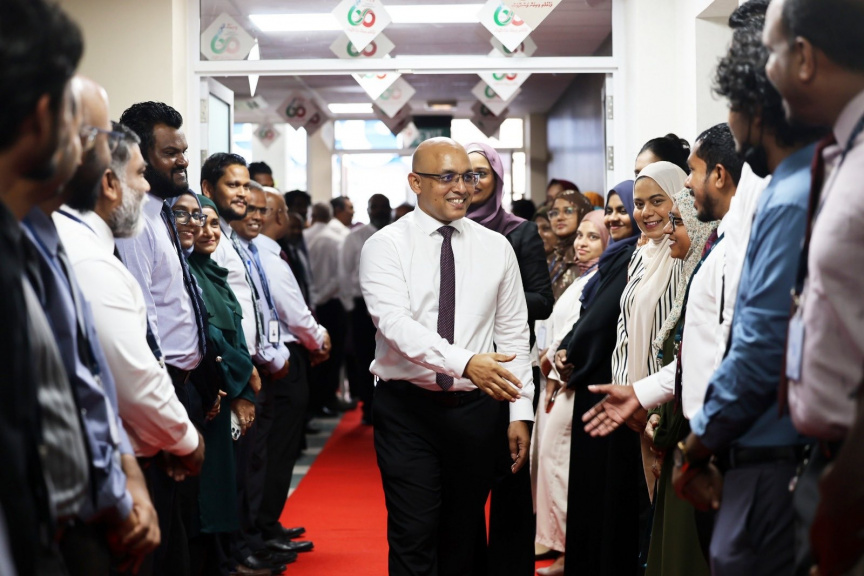
Finance Minister Hassan Zareer. (Photo/Ministry of Finance and Public Enterprises)
Global credit rating agency Moody’s has upgraded Maldives’ sovereign credit rating from Caa2 to Caa1 with a stable outlook.
The upgrade was announced by Moody’s on Thursday, and reflects the agency’s assessment that the Maldives’ near-term default risk has reduced materially following the successful repayment of major debt obligations this year.
This includes the repayment of the USD 500 million sukuk in April, the settlement of the USD 400 million currency swap facility from the Reserve Bank of India (RBI), alongside securities investments from the State Bank of India (SBI) totaling USD 100 million in May and September, and the rollover of the USD 100 million Eurobond until 2031.
The Finance Ministry said in a statement that the upgrade also reflects stronger foreign exchange inflows, and continued access to bilateral and multilateral financing.
Finance Ministry said that Moody’s also recognized the effective fiscal and monetary policy coordination between the government and the Maldives Monetary Authority (MMA), which strengthened the efficacy of the foreign currency revenue reforms, and the mandated foreign currency exchange into the domestic banking system.
“These foreign exchange measures implemented since 2024 and now expanded in 2026, will continue to bolster foreign currency inflows, thereby supporting the accumulation of the Gross International Reserves, and the Sovereign Development Fund (SDF),” said the ministry.
In addition to the reduced external debt servicing requirements in the near-term, the rating agency stated that the Maldivian government’s sustained access to bilateral and multilateral financing has continued to alleviate immediate liquidity pressures.
This includes additional financing amounting to USD 40 million from the World Bank, USD 50 million from the Asian Development Bank, USD 40 million from OPEC Fund.
The Finance Ministry added that the government was also actively engaging with development partners to meet financing requirements at concessional terms.
“Moving forward, the government will ensure that further budgetary financing is attained such that it does not adversely affect the overall debt sustainability of the Maldives,” said the ministry.
The Finance Ministry said that the Maldives’ public and publicly guaranteed debt- to-GDP ratio dropped to 122.6 percent by the end of July, describing this as a noteworthy decline from 129.2 percent at the end of 2025.
“The shift towards a sustainable debt trajectory is aligned with the government’s fiscal targets, and is a result of the implementation of prudent policies,” said the Finance Ministry.
The Finance Ministry noted that the ongoing conflict in the Middle East continues to weigh on the Maldivian economy, whilst posing downward risks primarily stemming from higher energy prices.
“In response, the government has implemented proactive measures to protect the vulnerable among the population from the adverse effects of the conflict, and remains steadfast in its commitment to supporting the functioning of the broader economy through appropriate and timely policies,” said the ministry.
Finance Ministry named attaining near-term macro-fiscal targets, improving the external sector position, and ensuring macroeconomic stability as key government priorities.
The ministry said that the government has rolled out key initiatives to achieve these targets, including accelerating renewable energy transition, and strengthening trade infrastructure focusing on increasing economic capacity, resilience and sustainability as the global economic conditions improve.
While Moody’s upgraded Maldives’ credit rating citing a material reduction in the government's near-term default risk, the agency warned that the country continues to face persistent fiscal, external and government liquidity risks.